All Categories
Featured
Key Financial Literacy Tips for Successful Consumers
Building Credit Through Advanced Financial Literacy Educa...
Evaluating Credit Repair and Financial Options
Table of Contents
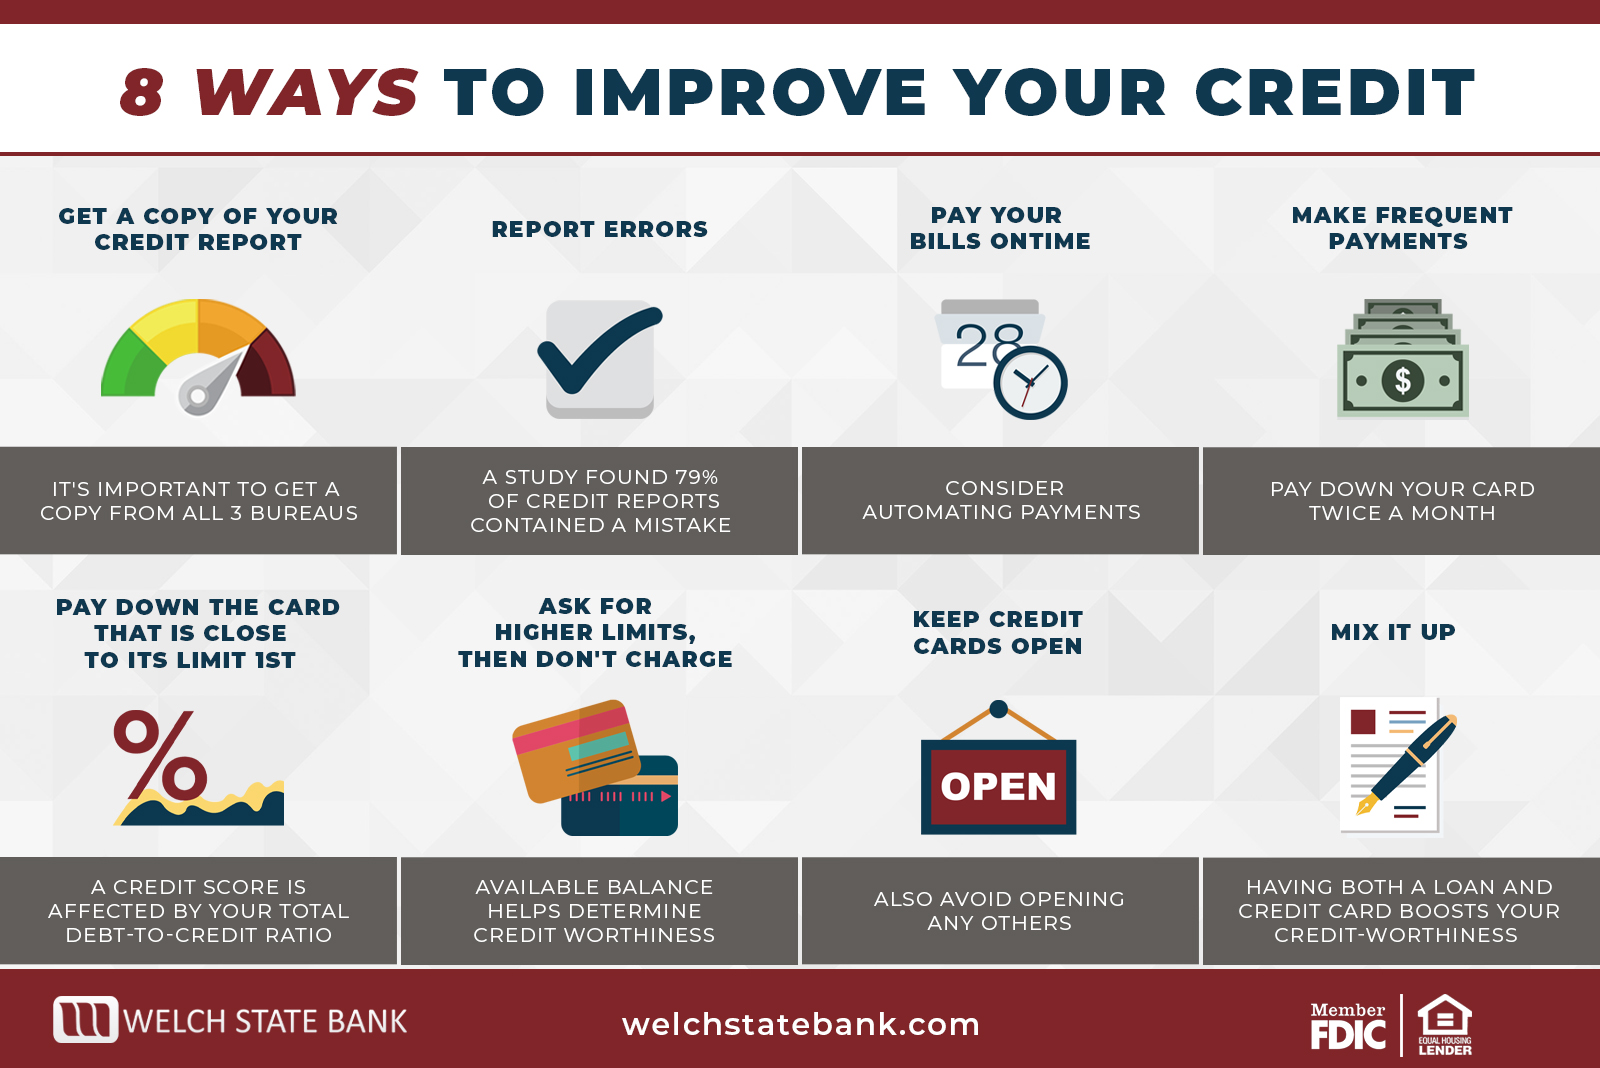
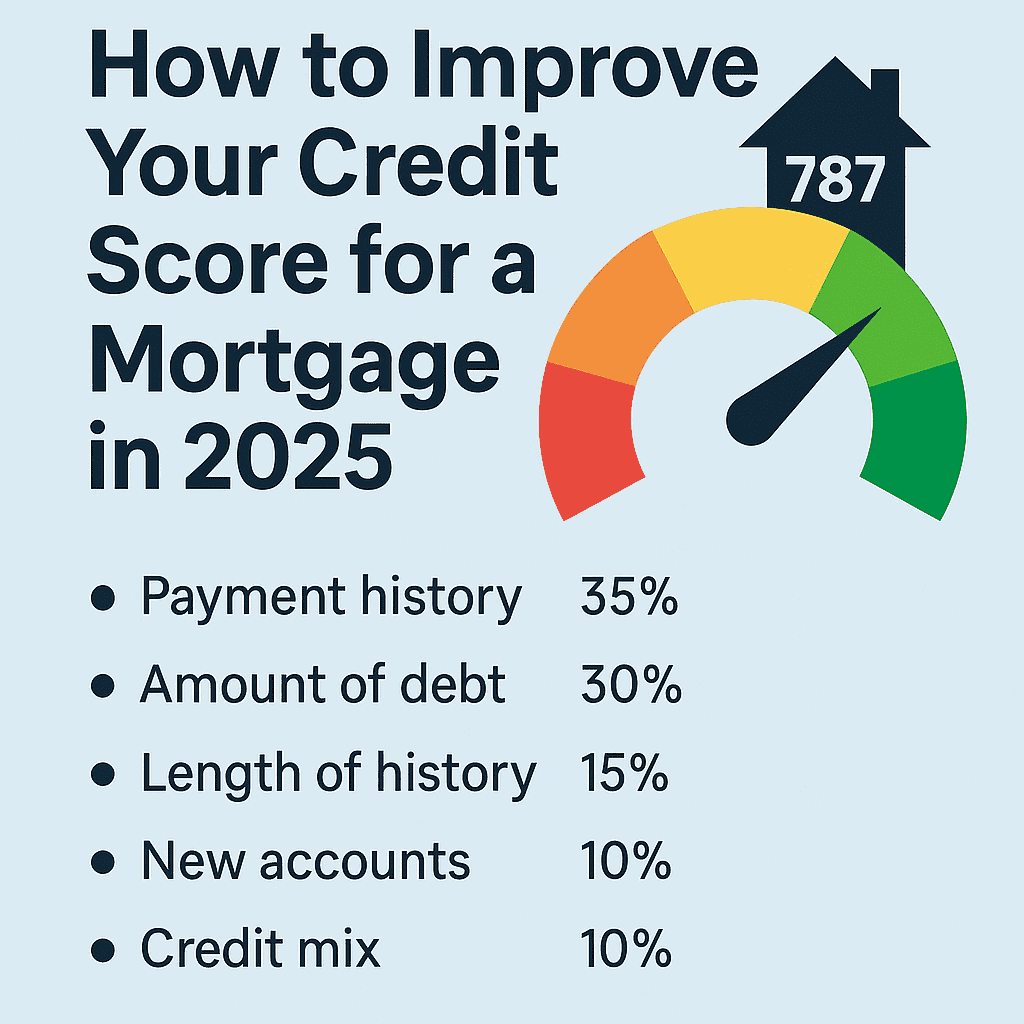
Results differ depending on how numerous missed out on payments you have and how far past due they are. Missed out on payments stay on your report for 7 years, however their impact fades over time. Your credit utilization ratio, the amount of credit you're utilizing versus what's readily available, represent 30% of your FICO Score and 20% of your VantageScore.
If yours is greater, paying down financial obligation is among the fastest methods to enhance your score. Think about using the financial obligation snowball or financial obligation avalanche approach to pay it down without otherwise impacting your rating. Within a month of your brand-new usage ratio being reported to the credit bureaus. That card's credit limit and history get factored into your own rating.
As an authorized user, the primary cardholder's habits affects your credit too. Once it's authorized and reported, it can lower your credit usage and increase your credit score.
Ask your company whether a tough query is required initially, as that can momentarily lower your score. Quick once the greater limit is reported to the bureaus, your usage ratio drops and your rating must follow.
You can likewise dispute the info if it's incorrect or too old to be listed. FICO 8, the most frequently used version, counts paid and overdue collections on financial obligations of $100 or more. Newer models, FICO 9 and 10, disregard paid collections entirely and deal with overdue medical collections less seriously.
Understanding the New Credit Repair Laws 2026Key Advantages of Free Financial Counseling Programs
Get personalized debt relief services that may minimize what you owe and help you gain back financial stability. These cards are backed by a money deposit (generally paid in advance), which serves as your credit line. They work like a routine charge card and report your payment history to the bureaus the very same method, so constant on-time payments build your score with time.
Not all scoring designs element in this information, but where it's considered, a constant record of on-time payments can meaningfully enhance your rating. As quickly as the info is reported to the bureaus.
Closing old accounts reduces your credit history and can increase your credit usage. Integrated, this could decrease your credit score.
Closing your earliest account minimizes your average account age, increases credit usage and can reduce your score when reported to the credit bureaus. It accounts for 10% of your FICO Score and is not factored into VantageScore at all. If you only have charge card, securing a small individual loan could boost your score.
Be wary of taking out brand-new credit just for the sake of improving your credit. Focus on organically mixing up your credit over time.
The Strategic Roadmap to Higher Credit Ratings
The time it takes will depend on the private aspects affecting it and the actions you take to change them. A credit line increase or becoming an authorized user can show outcomes within a billing cycle.
Understanding the New Credit Repair Laws 2026
Do not close old accounts, even ones you seldom use. For instance, keep your first charge card active by putting a little repeating charge on it, like a streaming membership, and pay it off every month. Closing old accounts reduces your credit rating and can increase your credit utilization. Integrated, this could decrease your credit rating.
Closing your earliest account minimizes your average account age, increases credit utilization and can lower your rating when reported to the credit bureaus. It represents 10% of your FICO Score and is not factored into VantageScore at all. If you only have credit cards, getting a small individual loan could boost your rating.
Be wary of taking out brand-new credit just for the sake of improving your credit. Focus on organically blending up your credit over time.
The time it takes will depend on the private aspects impacting it and the steps you take to alter them. A credit line boost or becoming an authorized user can reveal results within a billing cycle.
Effective Strategies for Fixing Your Credit Quickly
Closing old accounts shortens your credit history and can increase your credit utilization. Integrated, this might reduce your credit score.
Closing your oldest account reduces your average account age, increases credit utilization and can lower your rating when reported to the credit bureaus. It represents 10% of your FICO Rating and is not factored into VantageScore at all. If you only have credit cards, securing a little individual loan could enhance your score.
Watch out for getting new credit just for the sake of enhancing your credit, nevertheless. Focus on naturally blending your credit over time. Quick once the brand-new account is reported to the bureaus, you may see a change within a billing cycle. See LendingTree's complete guide on how your credit rating is computed.
The time it takes will depend on the individual elements impacting it and the actions you take to alter them. A credit line boost or ending up being an authorized user can reveal outcomes within a billing cycle.

Latest Posts
Benefits of Expert Financial Counseling
Modern Methods to Fix My Credit 2026
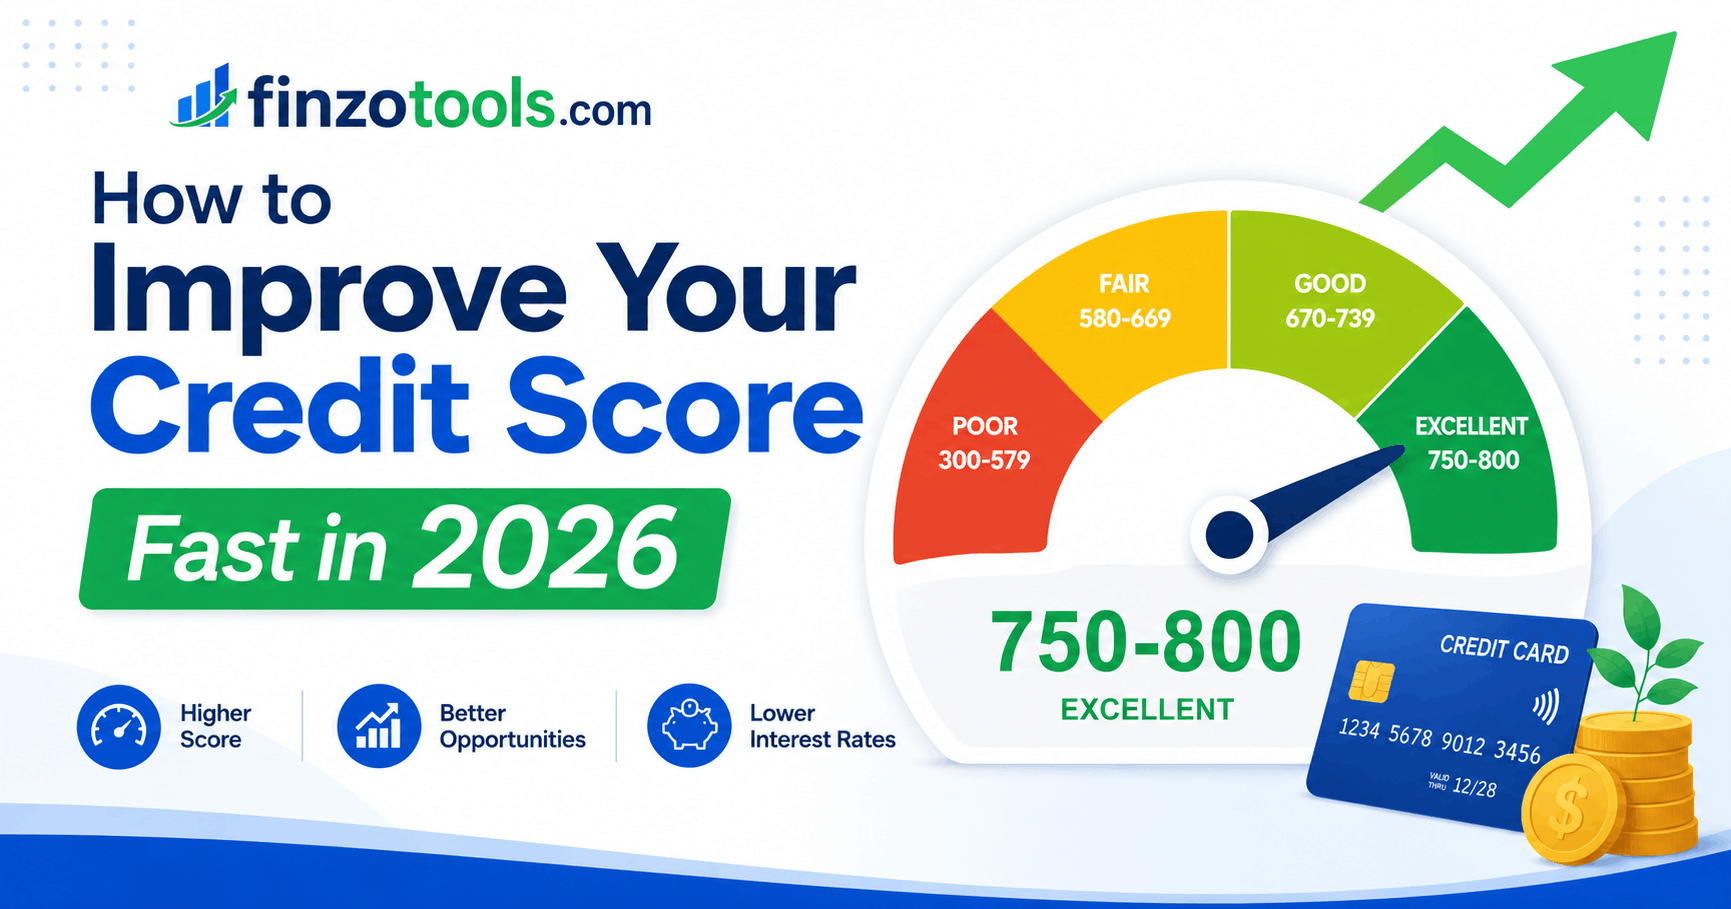
Key Financial Literacy Tips for Successful Consumers