All Categories
Featured
Key Financial Literacy Tips for Successful Consumers
Building Credit Through Advanced Financial Literacy Educa...
Finding Free Credit Counseling Near Me in 2026
Table of Contents
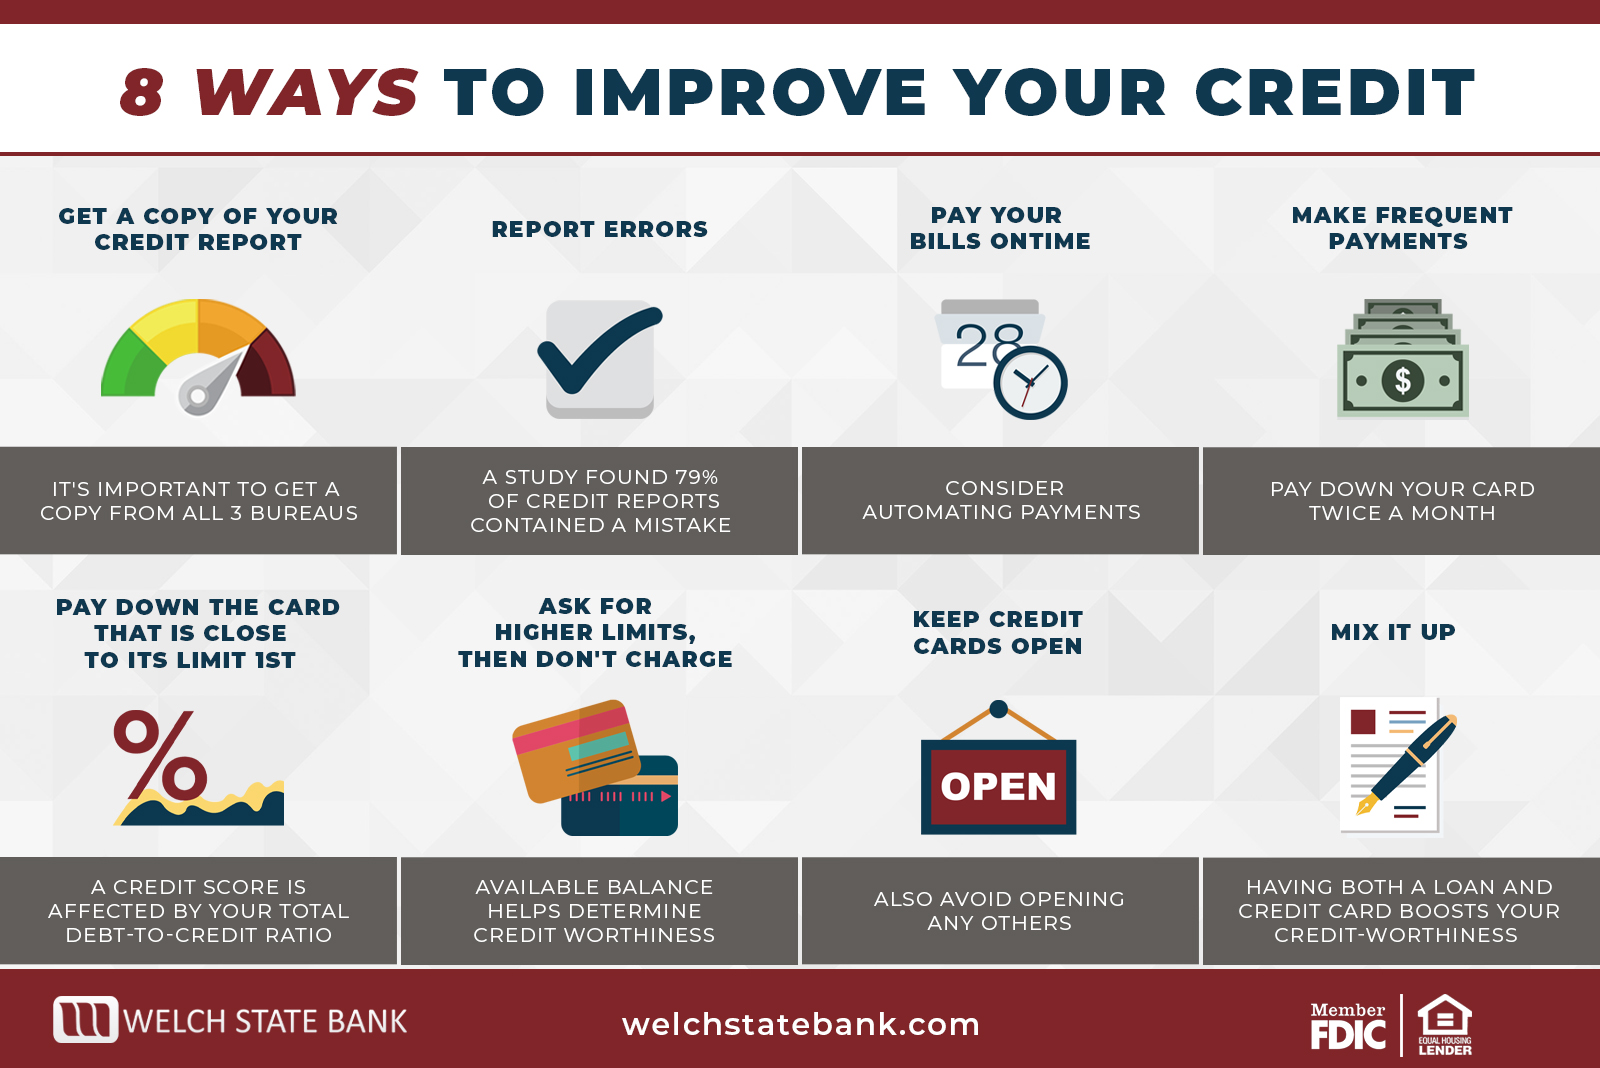
If you wish to repair your own credit: Visit to download complimentary copies of your credit reports from all three significant credit bureaus, which you can do when a week. Make sure to review your reports for any possible indications of credit mistakes or fraud. Send disputes to report inaccurate or deceptive details on your credit report.
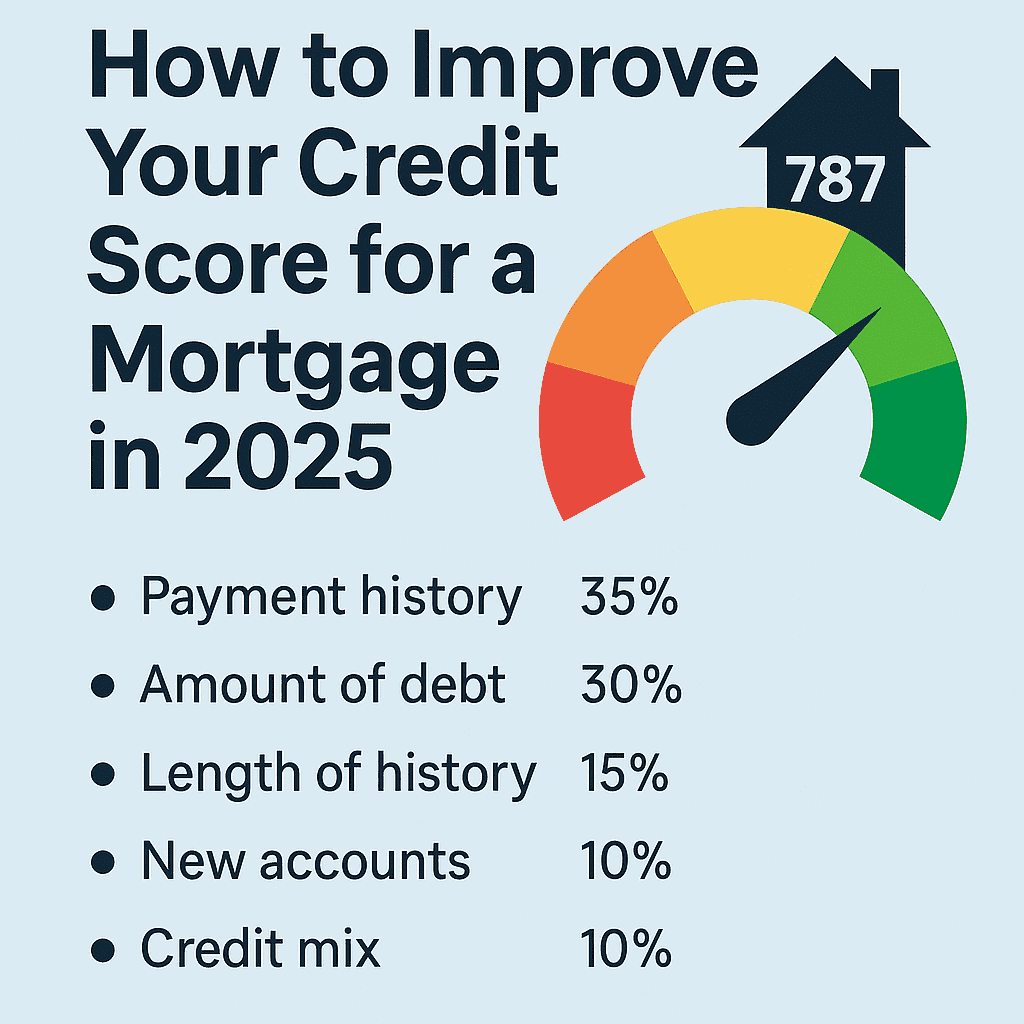
Guide to Financial Laws 2026If you have supporting documentation to support your claims, include it with your disagreement to enhance your odds of a successful investigation. Payment history is the most important consider your credit score worth 35% of your FICO Score and 41% of your VantageScore credit history. Paying on time will not technically fix your credit, but it can assist you avoid new credit history damage that might set back your effort.
Plus, reducing credit card debt has the added advantage of conserving you cash in interest charges. While you don't need to be afraid to apply for brand-new credit accounts in an accountable way, it's crucial to prevent letting lenders or credit card companies check your credit report excessively.
Monitoring your credit can assist keep you inspired throughout the credit repair work process and might inform you if any new negative details appears on your credit report. Credit repair business use to manage the credit repair process in your place. Essentially, you're hiring a third party to carry out a service that you choose not to do by yourself.
Generally, a credit repair work company begins by getting copies of your credit reports. Next, they recognize potential problems and dispute mistakes with the credit bureaus (and perhaps lenders as well) on your behalf.

A Guide to Improving Credit in 2026
Costs differ, but numerous companies charge a setup cost (often $70 to $200) and a monthly service charge varying from $50 to $150. It's also essential to comprehend that some business limit the number of disagreements they send out to the credit bureaus on your behalf per billing period. The purpose of limited conflicts is to slow down the disagreement process and extend the number of months a client stays in the credit repair work program, paying a month-to-month fee.
It's likewise essential to handle your expectations. Whether you work with a credit repair business or send out credit disagreements yourself, there is no assurance that accurate, negative information will be gotten rid of from your credit report right away. The credit bureaus can leave most negative products on your credit report for as much as seven years (ten years for specific insolvencies) unless there's a mistake.
Assures to get rid of precise information from your credit report Needs for in advance payment before finishing services No written agreement An agreement that doesn't consist of a cancellation policy Any claims of assisting you develop a "new credit identity" Encouraging you to lie (like making incorrect claims that you're a victim of identity theft) The Credit Repair Work Organizations Act (CROA) secures consumers from credit repair work scams.

Building Credit Through Advanced Financial Literacy Education
If you decide to employ a credit repair business, it is essential to do your research study to ensure you discover a credible service. Below are some suggestions to assist you get going. If you're dealing with a loan officer, fiduciary or another monetary professional, consider requesting for suggestions. Whether you get a referral or discover a credit repair company online, do some standard research study.
You can also look for complaints on the CFPB grievance database. Any legitimate credit repair business will follow CROA guidelines consisting of offering agreements, using consumers the right to cancel, not needing advance payment without services and not providing misleading info. It's also crucial to search and compare services from several credit repair work companies before you decide.
Both do it yourself credit repair and credit repair companies can only assist in specific situations. In many cases, other strategies might be a much better fit, specifically if your low credit score is due to high debt, missed out on payments or other precise but negative credit details that is going to remain on your credit reports for the foreseeable future.
It may remain on your credit reports for up to 10 years, and the credit score effect can be significant. Negative products fall off your credit report over time (7 to 10 years in a lot of cases).

Latest Posts
Benefits of Expert Financial Counseling
Modern Methods to Fix My Credit 2026
Key Financial Literacy Tips for Successful Consumers